Medicare Advantage Plans vs Original Medicare: Which Is Right for You?
When you first become eligible for Medicare, one of the most important decisions you’ll make is whether to go with Original Medicare or a Medicare Advantage plan. It’s a choice that affects your doctors, your costs, your coverage, and your flexibility – and it’s one that many people make without fully understanding the differences.
As an independent Medicare broker, I’ve helped thousands of people work through this exact decision. Here’s a clear, honest breakdown of how these two options compare – so you can make the choice that’s right for your specific situation.
What Is Original Medicare?
Original Medicare is the federal health insurance program administered directly by the government. It consists of two parts:
- Part A covers hospital care, skilled nursing facility care, hospice, and some home health services. Most people don’t pay a premium for Part A if they or their spouse worked and paid Medicare taxes for at least 10 years.
- Part B covers doctor visits, outpatient care, preventive services, and medical equipment. The standard Part B premium in 2026 is $202.90 per month.
Original Medicare does not include prescription drug coverage (Part D) or extra benefits like dental, vision, or hearing. Many people add a Medicare Supplement plan (Medigap) to cover the gaps in Original Medicare, and a standalone Part D plan for prescriptions. For a full breakdown of what Medicare costs, see our Medicare Costs guide.
What Is Medicare Advantage?
Medicare Advantage – also known as Medicare Part C – is an alternative way to get your Medicare benefits through a private insurance company approved by Medicare. These plans bundle Part A, Part B, and usually Part D into a single plan, and many include extra benefits like dental, vision, and hearing coverage.
You still pay your Part B premium with Medicare Advantage, but many plans charge $0 in additional premium on top of that. The tradeoff is that you typically must use the plan’s network of providers and may face prior authorization requirements for certain services.
Medicare Advantage vs Original Medicare – Side by Side
| Factor | Original Medicare | Medicare Advantage |
|---|---|---|
| Monthly premium | $202.90 (Part B) + Medigap premium | $202.90 (Part B) + often $0 plan premium |
| Provider choice | Any provider that accepts Medicare nationwide | Usually limited to the plan’s network |
| Out-of-pocket maximum | None (unlimited without Medigap) | Up to $9,250 in-network (2026) |
| Prescription drugs | Separate Part D plan needed | Usually included |
| Extra benefits | Not included | Often included (dental, vision, hearing) |
| Prior authorization | Rarely required | Common for procedures and specialists |
| Travel coverage | Any Medicare provider nationwide | Emergency only (most HMO plans) |
| Plan stability | Very stable year to year | Can change annually |
| Referrals needed | No | Often yes (HMO plans) |
The Key Differences That Matter Most
Cost Structure
Original Medicare with a Medigap supplement typically costs more per month in premiums, but offers very predictable out-of-pocket costs. Once you’ve paid your Medigap premium, most of your medical costs are covered regardless of how much care you use.
Medicare Advantage often has lower or $0 monthly premiums, but you pay copays and coinsurance every time you use the plan. For healthy people who rarely need care, this can mean significant savings. For people with frequent medical needs, the copays can add up to more than the premium savings.
Provider Access
This is where the two options diverge most significantly. Original Medicare is accepted by virtually every doctor and hospital in the country that participates in Medicare – with no network restrictions whatsoever. You can see any specialist you want without a referral.
Medicare Advantage plans restrict you to a network of providers. The size and quality of that network vary significantly from plan to plan and market to market. Before enrolling in any Medicare Advantage plan, it’s essential to verify that your doctors and preferred hospital are in the plan’s network.
Prescription Drug Coverage
Original Medicare doesn’t include prescription drug coverage. You need to add a standalone Part D plan separately. Most Medicare Advantage plans include Part D coverage as part of the bundle – which simplifies things and can save money, as long as your medications are covered on the plan’s formulary at an acceptable cost.
Extra Benefits
Original Medicare doesn’t cover dental, vision, or hearing. Medicare Advantage plans frequently include these extras. For people who need regular dental care or vision correction, these benefits can represent real value – though it’s worth looking carefully at what’s actually covered before counting on them.
Flexibility and Stability
Original Medicare with Medigap is remarkably stable. Your premium may increase modestly over time, but your coverage doesn’t change. Medicare Advantage plans can change their benefits, networks, and costs every year. This means you need to review your coverage annually to make sure it still works for you.
Which Option Is Right for You?
The honest answer is that it depends on your individual circumstances. Here are the factors that tend to point people toward each option:
Original Medicare with Medigap May Be Better If You:
- Have complex or chronic health conditions requiring frequent specialist care
- Have strong relationships with specific doctors or hospitals you don’t want to leave
- Travel frequently or split time between states
- Want maximum predictability in your healthcare costs
- Are concerned about prior authorization delays
Medicare Advantage May Be Better If You:
- Are generally healthy and don’t use a lot of medical services
- Want to keep your monthly costs low
- Have confirmed your preferred doctors are in-network
- Value extra benefits like dental, vision, and hearing
- Are comfortable reviewing your plan annually
For a deeper look at the Medicare Advantage side of this decision, our posts on Medicare Advantage pros and cons and the disadvantages of Medicare Advantage plans cover the key considerations in depth. And if you’re wondering whether Medicare Advantage is going anywhere, our post on are Medicare Advantage plans going away addresses that question directly.
For a full comparison of Medicare Advantage and Medicare Supplement plans side by side, see our detailed guide: Medicare Advantage vs. Medicare Supplement – Which Is Right for You?
One More Thing to Consider Before You Decide
If you’re enrolling in Medicare for the first time, you have a one-time opportunity to choose between these options with full Medigap availability. If you enroll in Medicare Advantage first and later want to switch to Original Medicare with Medigap, you may face medical underwriting in most states – meaning a Medigap insurer can deny you coverage or charge higher premiums based on your health history.
This is one of the most important things to understand before making your initial Medicare decision. It’s not a reason to automatically choose Original Medicare – but it is a reason to think carefully about your long-term health outlook before enrolling in Medicare Advantage for the first time.
If you’re just getting started with Medicare, our Turning 65 Complete Medicare Guide walks you through the entire process. And for a full explanation of your enrollment windows, see our Medicare Enrollment Periods Explained guide.
Get a Free Comparison Before AEP Closes
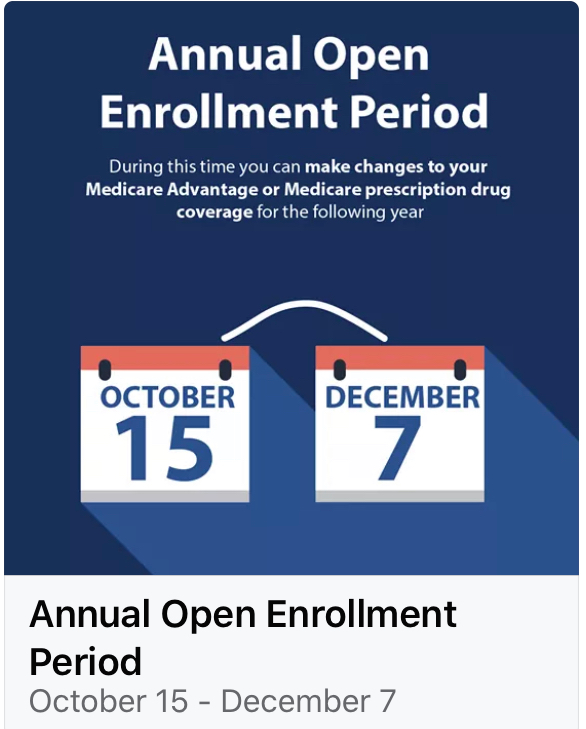
Medicare’s Annual Enrollment Period runs from October 15 through December 7. Whether you’re making this decision for the first time or reconsidering your current coverage, now is the time to act.
As an independent Medicare broker with 25+ years of experience, I compare Original Medicare and Medicare Advantage options across all major carriers at no cost to you. I don’t favor one option over the other – my job is to help you find what genuinely fits your needs.
Schedule your free AEP consultation today – or call me directly at 917-740-1895. Spots fill quickly as October 15 approaches.
We are not connected with or endorsed by the United States Government or the federal Medicare program. We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.

Craig Smith
Independent Medicare Insurance Broker | AHIP Certified
Craig Smith is the founder of Craig Smith Insurance Group, an independent Medicare brokerage serving seniors across New York, New Jersey, and nationwide since 2013. With over 25 years of financial services experience and 317+ five-star Google reviews, Craig helps clients compare Medicare Advantage, Medicare Supplement, and Part D plans — always free of charge.
Learn more about Craig →