Are Medicare Advantage Plans Good? An Independent Broker’s Honest Take
It’s one of the most common questions I hear: Are Medicare Advantage plans actually good, or are they too good to be true?
The honest answer is that it depends entirely on who you are, what your health needs look like, and what you value most in a health plan. Medicare Advantage plans are genuinely excellent for some people and genuinely wrong for others. The problem is that most of what you read online is written by people who have a financial interest in pushing you one way or the other.
As an independent Medicare broker, I don’t have that conflict. I represent all major carriers and get paid the same regardless of which plan you choose. So here’s my honest, unbiased take.
What Makes Medicare Advantage Plans Good
The Value Is Real for the Right Person
Let’s start with what Medicare Advantage does well because it does a lot of things well.
Many Medicare Advantage plans have $0 monthly premiums. You still pay your Medicare Part B premium of $202.90 per month, but on top of that, many plans charge nothing additional. Compare that to a Medicare Supplement plan, which typically runs $100 to $300 or more per month, and the cost difference is significant – especially for people on a fixed income.
Medicare Advantage plans also cap your annual out-of-pocket spending. In 2026, that cap is $9,250 for in-network services. Original Medicare has no such cap, which means your costs could theoretically be unlimited in a bad year. That protection matters.
And then there are the extra benefits: dental, vision, hearing, fitness memberships, over-the-counter allowances, and more. These aren’t available through Original Medicare at all. For people who actually use them, they represent real, tangible value.
Millions of People Are Happy With Their Plans
More than half of all Medicare beneficiaries are now enrolled in Medicare Advantage. That’s not a marketing statistic, it reflects the reality that for a large portion of Medicare-eligible Americans, these plans are working well.
People who are generally healthy, see their doctors regularly but don’t have complex needs, and have confirmed that their preferred providers are in-network tend to do very well with Medicare Advantage. They get comprehensive coverage, extra benefits, and keep more money in their pocket every month.
When Medicare Advantage Plans Aren’t the Right Fit
Here’s where I need to be direct with you – because this is where people get hurt.
Network Restrictions Are a Real Problem for Some People
Most Medicare Advantage plans, HMO plans, require you to use a specific network of doctors, hospitals, and specialists. If your preferred doctor isn’t in the network, you’ll either pay significantly more or need to find a new provider.
This isn’t a hypothetical concern. Networks change every year. Doctors drop off plans. Hospital systems renegotiate contracts. I’ve seen clients who were perfectly happy with their Medicare Advantage plan face a difficult situation when their longtime physician left the network mid-year.
Prior Authorization Can Delay Care
Medicare Advantage plans can require prior authorization before approving procedures, specialist visits, or certain treatments. The insurance company has to approve the service before you receive it. For most routine care, this isn’t an issue – but for people with serious or complex health conditions, authorization delays can be genuinely disruptive.
Copays Add Up for Frequent Users
The $0 premium looks great on paper, but every time you use the plan, you pay copays and coinsurance. Doctor visits, specialist appointments, lab work, hospital stays – each one comes with a cost. For people who use a lot of healthcare services, those copays can add up to more than the premium savings over the course of the year.
Switching Back to Original Medicare Can Be Difficult
This is the factor that concerns me most when talking to clients. If you enroll in Medicare Advantage and later decide you want to switch back to Original Medicare with a Medigap supplement, you may face medical underwriting in most states. That means the Medigap insurer can review your health history and potentially deny coverage or charge significantly higher premiums.
In other words, once you’ve been on Medicare Advantage for a while, returning to Medigap may not be possible at standard rates or at all. That’s a long-term consequence that deserves serious consideration upfront.
So Are Medicare Advantage Plans Good? Here’s My Honest Answer
Yes – for the right person, Medicare Advantage plans are genuinely good. The value is real, the extra benefits matter, and the cost savings can be significant.
But they’re not universally good. For people with complex health needs, strong relationships with specific providers, or who travel frequently between states, the network restrictions and prior authorization requirements can create real problems. And the difficulty of switching back to Medigap later is a risk that every new enrollee should understand before making a decision.
The right question isn’t whether Medicare Advantage plans are good in the abstract. It’s whether a Medicare Advantage plan is good for you specifically – your doctors, your health, your budget, your priorities.
That’s exactly the conversation I have with every client. For a full side-by-side comparison of your options, see our guide on Medicare Advantage vs. Medicare Supplement. And if you want to understand the full picture, including the drawbacks, our post on Medicare Advantage plans pros and cons covers both sides in depth.
How to Know If Medicare Advantage Is Right for You
Here are the questions I walk every client through:
- Are your current doctors and preferred hospital in the plan’s network?
- Do you take prescription medications, and are they covered on the plan’s formulary at an acceptable cost?
- How often do you use healthcare services, and what will your copays add up to over the year?
- Do you travel frequently or spend part of the year in another state?
- Are you comfortable with the possibility that your network may change next year?
- Do you understand what it would take to switch back to Original Medicare later if you wanted to?
If you can answer those questions confidently and Medicare Advantage still looks like the right fit, it very well may be. If any of those questions give you pause, that’s worth exploring before you enroll.
For new Medicare enrollees, our guide to choosing the best Medicare Advantage plan walks you through the selection process step by step. And if you’re just getting started with Medicare, our Turning 65 Complete Medicare Guide covers everything you need to know.
Get a Free, Unbiased Opinion Before You Decide
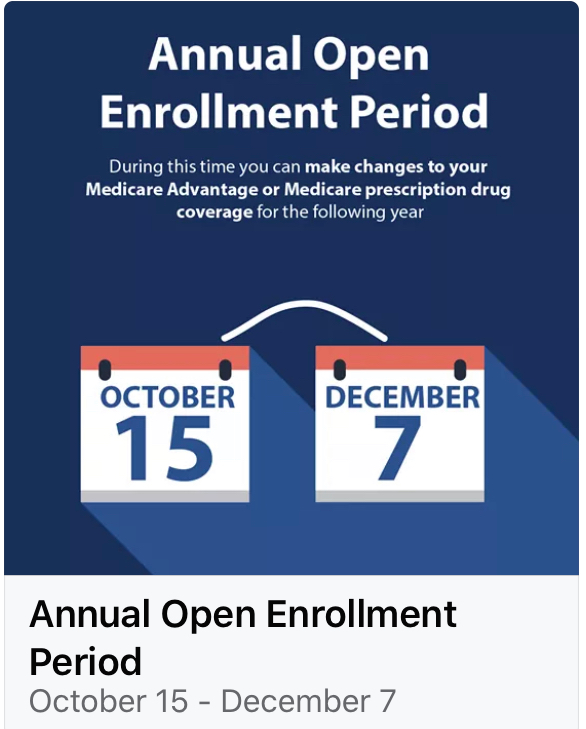
Medicare’s Annual Enrollment Period runs from October 15 through December 7. If you’re currently on Medicare Advantage and wondering whether it’s still the right plan for you, now is the time to review. If you’re new to Medicare and trying to decide between Medicare Advantage and a Medigap supplement, the earlier you start that conversation, the better.
As an independent Medicare broker with 12+ years of experience, I compare plans across all major carriers at no cost to you. My job is to help you find the plan that genuinely fits your needs – not to push you toward any particular option. You can also review all your Medicare enrollment period options to make sure you’re acting at the right time.
Schedule your free consultation today – or call me directly at 917-740-1895. I’m happy to walk you through your options and give you a straight answer.
We are not connected with or endorsed by the United States Government or the federal Medicare program. We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.

Craig Smith
Independent Medicare Insurance Broker | AHIP Certified
Craig Smith is the founder of Craig Smith Insurance Group, an independent Medicare brokerage serving seniors across New York, New Jersey, and nationwide since 2013. With over 25 years of financial services experience and 317+ five-star Google reviews, Craig helps clients compare Medicare Advantage, Medicare Supplement, and Part D plans — always free of charge.
Learn more about Craig →